Introducing a new model for forecasting PE outcomes
Included in the July 2023 issue of The Journal of Portfolio Management, our paper “Takahashi–Alexander Revisited: Modeling Private Equity Portfolio Outcomes Using Historical Simulations” introduces a new approach to cash flow forecasting.
Dawson Beutler, Alex Billias, Sam Holt, Josh Lerner, and TzuHwan Seet
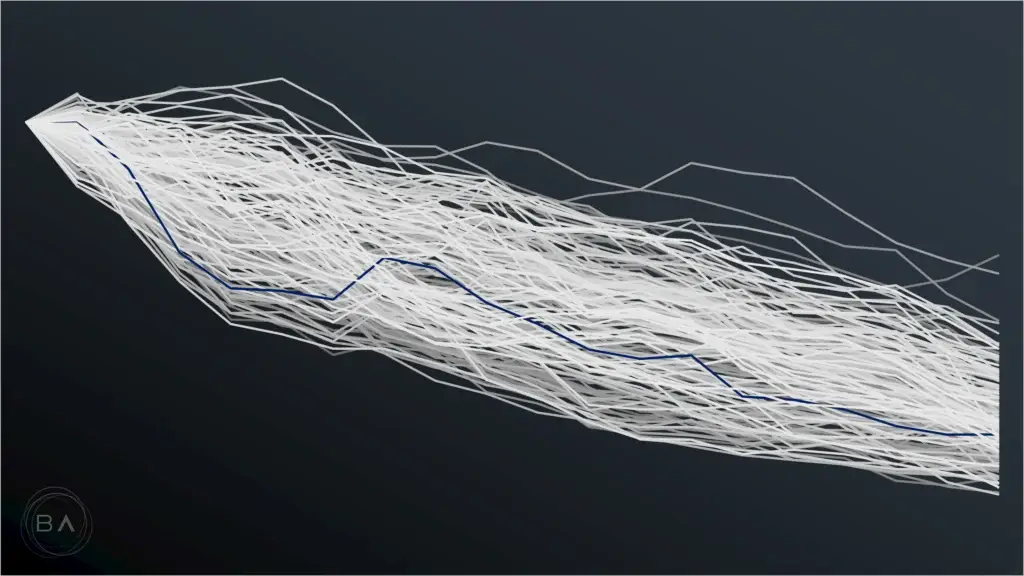
Abstract: In 2001, Dean Takahashi and Seth Alexander of the Yale University Investments Office developed a deterministic model for estimating future cash flows and valuations for the Yale endowment’s private equity portfolio. Their model, which is simple and intuitive, is still commonly used by investors to this day. However, the model possesses significant shortcomings, including its sensitivity to the assumptions necessary for the model to function and its failure to provide a range of possible portfolio outcomes. Both issues can result in investors developing overconfidence in forecasts, which can result in suboptimal (or even adverse) portfolio management decisions. To address these shortcomings, we propose a novel historical simulation approach that preserves the simplicity and intuition behind Takahashi and Alexander’s approach. However, our model, which leverages historical private equity cash flow data, requires no user assumptions and naturally provides a range of outcomes. We explore this model in some depth, highlighting the model’s power and flexibility across myriad use cases.
See this forecasting model run on your own funds. Bella’s platform applies the historical-simulation approach introduced here to your portfolio, producing cash flow projections you can actually plan around.